


Anxious about the encroaching SAVE deadline? You are not a loan. This is the landscape student debtors face: anxiety and confusion, intrusive emails and calls from scammy servicers, politicians who talk about “affordability” but ignore the financial stressors debtors navigate on a daily basis. And, worst of all, a student debt balance that refuses to go down no matter how much hard-earned money you throw at it. Fact is, whether or not you carry a balance of your own, families, cities, states, and our entire nation is burdened by the student debt crisis.

At Debt Collective, we believe debtors deserve tools to get as close to zero monthly payments as possible, but as the terrain shifts, so must our strategies. When we debtors share information collectively — when we move in concert instead of isolation — we can better ride out bureaucratic storms. That’s why we’re providing the following tips to help you reassess your options as the SAVE deadline draws near.
Earlier this summer, we suggested not to rush. We told you to ignore the incendiary, cruel, and alarmist messaging from the Department of Education telling you to immediately leave the SAVE repayment program. There was (and still is) ongoing litigation around SAVE, which could have made a switch in repayment premature and unnecessary — and given the likely possibility of Federal Student Aid bungling the transition, extremely costly as well.
Given the updated information we now have about SAVE litigation, the impending deadline for many student debtors, and the possibility of locking in a slightly lower interest rate, we think it may be time for you to reevaluate your options. Below, we’ve provided our most detailed description of facts to consider, including a little-known possibility to force a delay in repayment.
Americans deserve better than what our federal government is offering us. We deserve debt abolition. We hope you’ll join us in this fight!
Factors to Consider
The 90 Day Message from Your Servicer
Many of you have already received an email from your servicer starting a 90-day clock to switch out of SAVE. If you haven’t yet, you likely will, we just don’t know when.
According to the Trump administration, if you don’t pick a new plan within 90 days, they will punish you by automatically enrolling you in the most expensive plan, the Standard Repayment Plan. This is cruel. If this happens to you, know that you can switch to a cheaper plan after the auto-enrollment if a cheaper plan is available. This punishment is not fully binding.
What If You Cannot Afford Any of the New Repayment Plans?
Use the EDCAP calculator to find out what your payments will be under other plans. Depending on family size and income, some people can still qualify for $0 monthly payments under Income Based Repayment (IBR with a B). But for many people, $0 monthly payments will not be an option and being forced into repayment will mean being forced into delinquency and default.
However, there is an option to buy yourself more time that we haven’t seen anyone else talk about.
Instead of authorizing the Department of Education to access your taxes from last year, you can verify your income through alternative methods. This means submitting the last several months of paystubs, or using bank statements. It is more paperwork for you, but it is also a more difficult and time-consuming process for loan servicers and the Department of Education.
If you switch to an income-driven repayment plan and verify your income through alternative methods, it can delay the processing time, sometimes significantly. During that time, your loans should be kept in an administrative forbearance. Interest will still accrue, but you won’t owe any payments. For people who are simply trying to avoid default for as long as you can, this is a way to delay. Here is a guide on how to verify your income using alternative methods.
If you are in default, please RSVP for our upcoming 10/6 default office hours.
What’s Going on with SAVE Litigation?
There is one ongoing lawsuit that could impact your ability to stay in SAVE, along with the best alternative plans if you do switch. It is called Havens v. U.S. Department of Education. The judge has not made a decision in this lawsuit yet, and we have no idea when they will.
We cannot predict what will happen, but there is a chance that the judge will pause the transfer of student debtors off of SAVE, which would put many debtors back into forbearance. It may be that by the time we hear the judge’s ruling, the best time to switch will have already passed for you.
Autopay Interest Rate Reduction
If you enroll in autopay by September 30th, the Department of Education claims you will get a 1% interest rate deduction.
Now, for some context. In the past, federal student debtors have been given a 0.25% interest rate reduction if they enrolled in autopay. Dept. Ed is making a 1% rate reduction available for the next two years if you meet this deadline.
If you can afford to make a payment under a different plan, and you have already received the 90-day email from your servicer that will soon force you into repayment anyway, you may want to consider getting the 1% interest rate reduction.
Of course, how meaningful this reduction is depends on your current interest rate, the size of your student loans, and how close you are to triggering cancellation in one form or another. You’ll want to make that careful determination for yourself.
But for people who are still on the SAVE forbearance, there is a catch: your servicer will not let you enroll in autopay while in forbearance, and the amount of time it will take to process a switch to another plan will likely take long enough that it will cause you to miss the Sept 30th deadline.
However, there is still a way to do it. You can fill out a paper application to enroll in autopay and upload it to your servicer by Sept 30th.
If your servicer is EdFinancial, the form you need is here.
For MOHELA, the form you need is here (NOTE: this link will trigger an automatic download of the PDF).
For other servicers, call and ask them for a paper form to enroll in autopay.
Keep good documentation. If your servicer does not honor this 1% interest rate reduction — even if you file the paperwork by the deadline — there may be possible legal action that can be taken.
NOTE: There are risks to consider with enrolling in autopay. Because your servicer will be automatically debiting your bank account, there is a risk of overdraft and overdraft fees from your bank. You should have a clear sense of what your monthly payment will be and when the due date is and plan accordingly. You should also take care to recertify your income 11 months after enrolling in a new Income-Driven Repayment plan. If you forget to recertify your income, you will be switched into the standard plan and will likely have a higher payment. That higher payment would then be automatically deducted from your bank account.
In the event that you experience any loan servicer errors, please use this form to document them.
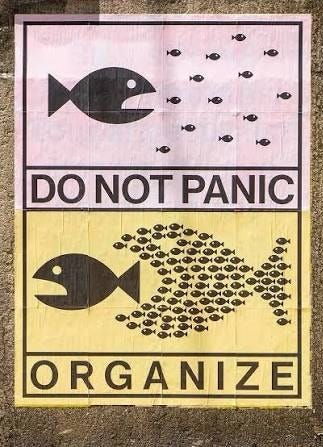
We know this is stressful and confusing. That’s why we held an emergency webinar on all things SAVE. Watch the webinar recording and share with your friends and family who are considering their repayment options.
This is also a moment to organize for a pause on all federal student loan payments and interest. Join our national call to demand a payment pause next Wednesday 9/23 at 8 pm ET / 5 pm PT. We cannot navigate this alone — and we have a track record of improving people’s financial situations based on our organizing. We need you in this fight!
RSVP for 9/23 National Call to Demand a Payment Pause
As the nation’s first and only debtors’ union — with members from across the country numbering in the tens of thousands — we’re building collective power to fight for a debt-free future, universal healthcare, social housing, and free college. Our vision isn’t limited to our individual debt balances or the hope of relief. It’s about organizing for a jubilee and a total and complete shift in society — true debt abolition. And we need all hands on deck to get us there.

Can you share this post with someone else who might need it?
In the meantime, remember to be kind, compassionate, and patient with yourself. If the student debt system feels Kafkaesque, that’s because it was designed that way.
Trump, like any other president, has the power to pause and cancel all federal student debt, which would boost our economy over time. Instead, he’s giving tax breaks to billionaires and making illegal promises to pay $5000 if people vote for him — a bribe with a comparably far greater price tag compared to mass debt relief.
Hope is a discipline, and thankfully, we’re in it for the long haul. We invite you to make Debt Collective your organizing home amidst the mayhem. We sincerely hope to see you at one of our upcoming meetings!
Remember, alone our debts are a burden, but together, they make us powerful.